The first two parts of this series covered how we managed our accounts and talked about money. This final part brings those ideas into the budget: what needed paying, what we wanted to save for, and how investing fitted into our plan for financial independence.
This is the practical side of our story, with examples and resources you can use to think through your own household. It isn’t a promise that following the same steps will produce the same result.
Start with what your life actually costs
We used spreadsheets to track our finances and project our net worth. It helped turn a distant FIRE goal into something we could work on. But a useful projection needs a realistic starting point.
For a household budget, list the money coming in and the money going out. Include the ordinary bills, the less frequent ones, and the things you want to make room for. If the budget leaves out how you actually spend, it won’t tell you much.
The Consumer.gov budgeting guide has a straightforward worksheet if you’re starting from a blank page. In Part 1, I shared how we used a joint account to fund agreed expenses while keeping some personal spending separate.
Give annual bills a monthly place in the budget
Annual expenses can make an otherwise ordinary month look expensive. A simple way to plan for them is to divide the expected annual amount by twelve and include that amount in your monthly budget.
These figures come from the sample budget I put together in 2023. They illustrate the calculation; they aren’t current prices or an estimate of what your life in Portugal would cost.
| Expense | Annual amount | Monthly amount |
|---|---|---|
| Ring insurance | $100 | $8.33 |
| Tax preparation | $1,200 | $100.00 |
| Car maintenance | $200 | $16.67 |
| Car registration | $800 | $66.67 |
| Total | $2,300 | $191.67 |
See the original sample budget
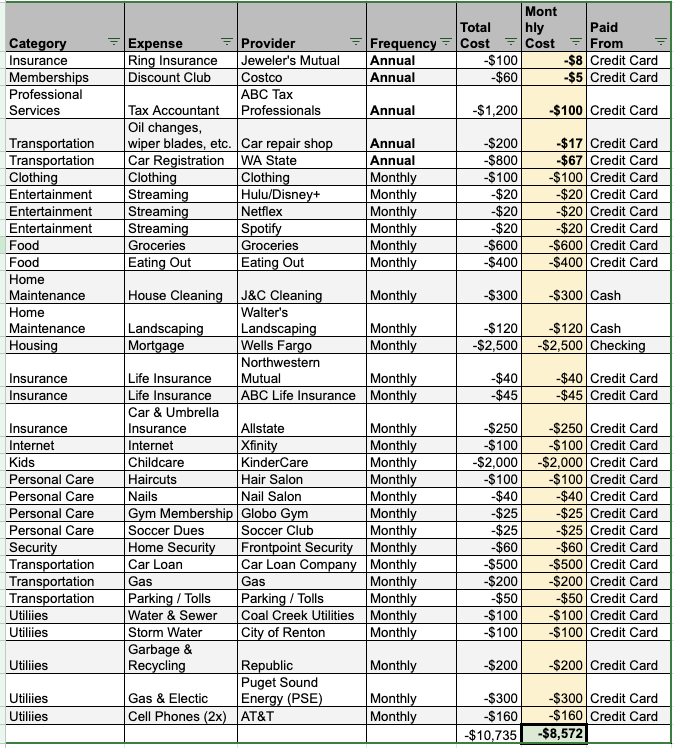
The same idea can work for a vacation fund, gifts or another planned expense. Estimate the amount and the date, then work backward. An expense due in four months needs a different calculation from one that is a year away.
Separate money needed soon from money for later
A bill due next month and a retirement goal years away have different jobs. Before deciding where to put money, ask when you expect to use it and what would happen if its value fell.
- Everyday bills: what needs to be available before the next payday?
- Planned expenses: what do you know is coming, even if it isn’t monthly?
- Unexpected costs: what cash reserve would help you handle a repair, lost income or another financial shock?
- Longer-term goals: which money can stay invested, and what risks can your plan accommodate?
The CFPB’s emergency-fund guide explains how to think about a reserve for unexpected expenses. The right amount depends on your situation. Investor.gov’s guide to asset allocation and diversification explains how time horizon and risk fit into investment choices.
Make room for debt and the goals you care about
Our goals included paying off my student loans, paying off our cars, and no longer carrying credit card balances. We also wanted to travel, have children, buy property and eventually move abroad. Those goals had to fit into the same household finances.
That’s why the conversations in Part 2 mattered. It was easier to discuss a spending choice when we understood the bigger goal behind it.
For your own budget, list debts with their balances, interest rates, minimum payments and due dates. Then agree on an approach you can afford to maintain. The Your Money, Your Goals toolkit includes tools for tracking debts and making a debt action plan.
Increasing income was part of our approach too, but that didn’t make every idea a success. I’ve written about the side hustles I started and stopped. There’s useful information in the false starts as well as the wins.
Automate the parts that don’t need a new decision
We used payroll deductions for our 401(k) contributions and direct deposit to send money to the accounts we used for household bills and personal spending. We also set recurring bills to autopay.
Our arrangement changed when my earnings became variable. Later, when we returned to a mix of shared and individual spending, we adjusted it again. The system had to work with the money actually coming in.
If you automate transfers, leave enough room for bills and check that the dates fit your pay cycle. For US retirement accounts, use the IRS’s current 401(k) contribution-limit information and IRA contribution rules. Eligibility and tax treatment need their own review, especially when you live abroad.
The funds we’ve held along our FIRE journey
Our investing story includes broad stock-market index funds, a Nasdaq index fund, inflation-protected bonds, and a concentrated investment in semiconductors. Our mix has changed over the years. The funds below were part of our household’s holdings when we reviewed our allocations in October 2026.
The four funds listed here are mutual funds. FXAIX, FNCMX and FIPDX are index mutual funds; FSELX is actively managed. Index funds can also be structured as ETFs, but that isn’t the structure of these particular funds.
| Fund | Type | What it invests in |
|---|---|---|
| FXAIX Fidelity 500 Index Fund | Stock index mutual fund | Large US companies through the S&P 500. |
| FNCMX Fidelity Nasdaq Composite Index Fund | Stock index mutual fund | Stocks represented in the Nasdaq Composite Index. |
| FIPDX Fidelity Inflation-Protected Bond Index Fund | Bond index mutual fund | The inflation-protected US Treasury bond market. |
| FSELX Fidelity Select Semiconductors Portfolio | Actively managed sector mutual fund | Companies in semiconductors and related businesses. |
FXAIX has been part of both our joint-account and retirement-account investing. FNCMX has appeared in our retirement holdings, and FIPDX in our joint account. These holdings give a more complete picture than saying that we invested in “the stock market.”
The semiconductor investment that became a big part of my story
In 2018, I went big on FSELX inside my rollover IRA. That position grew substantially and became an important part of my financial-independence story. It was a concentrated bet on one industry.
As that holding grew, so did the question of how much of our future we wanted tied to one industry. Our later allocation conversations included reducing semiconductor concentration and considering a broader mix of investments.
A good outcome doesn’t remove the risk we took to get there. Fidelity notes that FSELX’s narrow industry focus can make it more volatile than a diversified fund or the broader market. It’s part of our experience, not a template for someone else’s retirement plan.
What holding several funds does—and doesn’t—tell you
Four fund names don’t automatically mean four independent sources of risk. Stock funds can own some of the same companies. The useful questions are what each fund holds, how those holdings overlap, and how much of the household’s total portfolio is exposed to the same companies or industry.
FIPDX also needs a different description from the stock funds: it holds inflation-protected bonds, but it isn’t cash and its value can fall, including when interest rates move.
The table records funds we’ve held. It doesn’t set out a current allocation or a percentage mix for readers to copy.
If you’re comparing funds, review the objective, holdings, risks and costs on the official fund pages linked above. Investor.gov’s index-fund explanation, diversification guide and fund-fee guide are useful starting points. For longer reading, explore JL Collins’s Stock Series.
Track progress without treating a projection as a promise
I got very enthusiastic about our spreadsheets. Seeing our projections turn into progress helped me believe financial independence was possible for us.
A projection is still a set of assumptions. Spending changes. Markets move. Work, family needs and health can change too. A useful review asks both “What do the numbers say?” and “Does this still describe the life we want?”
If you’re working toward a FIRE number, read our FIRE journey for the basic idea and resources. A financial-independence target needs to account for spending, taxes, healthcare and how long the money may need to last; it isn’t the same thing as reaching a net-worth milestone.
When the plan includes moving abroad
Our money setup changed again after we moved from the US to Portugal in 2022. We had accounts in two countries, expenses in another currency, and a new set of practical decisions to make.
Part of the preparation is researching everyday costs, housing, schools and healthcare. Part of it is getting qualified advice about the tax and investment questions that cross borders. A familiar US account or rule isn’t the whole plan.
Read the full Marriage and Money series
- Part 1: Managing money as a team — Accounts, shared expenses and changing income.
- Part 2: Moving past fear to FIRE — Money stories, conversations and shared goals.
- Part 3: Budgeting and investing — Turning the conversations into a practical plan.
This post shares personal experience and general educational information, not individualized investment, financial or tax advice. Examples are illustrative. Resources reviewed in November 2026.